Malicious cases filed against the Tax-Free status of the Charitable Trusts
This text was machine-transcribed from the printed book and may contain errors. Select the words and choose “Report a mistake”.
In 2010, along with the religious persecution that hit His Divine Holiness Paramahamsa Nithyananda and His disciples in an onslaught of violent attacks, a number of previously closed tax related cases were deliberately re-opened, calling into question the tax-free status of the charitable trusts and their rightfully claimed donations. The cases were eventually closed as the commissioner found no fraudulence in any of the Aadheenam’s (temple monastery complexes) financial dealings, but not before the ordeal caused much pain and suffering to devotees.
His Divine Holiness Paramahamsa Nithyananda spoke thus when he blessed his disciples to register the charitable trust in the initial years: “Integrity, economic chastity and dharma (an unwritten discipline) are the pillars on which the accounts and finance teams of Nithyananda Mission stand.”
Nithyananda Peetham prides itself in keeping clear ‘books’ and has always been free of black money. All the donations are properly accounted for, catalogued, and receipts are issued to the donors. There has never been any concealment of income or misappropriation of funds. This is why none of the trust cases were ever selected for compulsory scrutiny; the trust is always able to show the clear and complete paper trail that accounts for every rupee donated and every rupee spent.
How is it that the charitable trust was used in an illegal attack that threatened the very lives of aadheenavasis living at Nithyananda Peetham Bengaluru Aadheenam? Income tax collection and management is a function of the central government in India, which applies to individuals as well as organizations.
Trust name - Nithyananda Dhyanapeetam
Nithyananda Dhyanapeetam is a registered public charitable trust, which has a tax exemption for donors as well as the organization. However, during the time of the media attack against Paramahamsa Nithyananda, in an illegal attempt to seize the money on which the residents of the adheenam survived, the income tax assessments were re-opened, in a ruthless attempt to grab money from the already suffering monastic community.
The income tax department claimed to suspect concealment of income by the Trusts, and hence issued notice u/s.148 of the Income tax Act of 1961 in August, 2010, to all the Trusts and re-opened all the cases (which had previously been closed) from the time of their inception in 2005-06.
Here is the Nithyananda Dhyanapeetam case for Assessment Years 2006-07, 2007-08, 2008-09 and 2009-10. For all these years notice u/s.148 was issued on 30/08/2010 to reopen the assessments and ascertain the anonymous donation within the meaning of Sec.115BBC and charge tax at the maximum marginal rate. The assessing officer justified his decision to re-open the assessment by making a huge addition, however, the ld. Commissioner of Income tax (appeals) knocked down all the demands, stating that even the reopening of the assessment is completely against the law.
The Commissioner of Income tax (appeals) - CIT(A) - has very clearly mentioned that the assessment reopened is unlawful. The income tax Department's Appellate authority gives a crucial expert opinion as to the illegality of the attack against the organization's donations. The most important point to be noted here is that the department did not file any appeal against this order with Income tax Appellate Tribunal and accepted the order of CIT(A).
Although the ordeal ended in victory on behalf of Nithyananda Dhyanapeetam, the case took a severe toll on the well being of many innocent people.
"For three weeks, we had to live on rations meant for a few days," says Ma Nithya Brahmanjnananda, as she wipes away tears that show the pain is still fresh, even years after the incident. "When the accounts were frozen, I was among a team of volunteers led by Ma Lokanayaki, Paramahamsa Nithyananda's own mother. She sat for hours on end, picking through bags of rotting dhal, painstakingly separating the good lentils from the bad. She was covered in bugs but kept working so that we could all eat."
We often forget the human toll taken by illegal government actions and corporate decisions. In the myriad false cases against Nithyananda Dhyanapeetam, however, the cost to human life can never be ignored.
Below is an excerpt from the case, showing Nithyananda Dhyanapeetam's full cooperation with the tax office, and open accounts: :2:
Sec. 115BC. On account of that there is a reason to believe income escaped for assessment. Hence notice u/s 148 was issued on the assessee on 18/8/2010.
In response to the notice the assessee submitted a letter dated24/9/2010 seeking the reasons for reopening the assessment in writing. The same was offered to the assessee vide this office letter dated 29/9/2001. Consequently the assessee representative submitted the letter dated 24.9.2010 requesting to accept the return of income file on 30/9/2008 as return in response to the notice u/s 148. Later notice u/s 143(2) was issued on the assessee on 20/11/2010 calling for various details.
The assessee representative Mr. Sachin Kumar, Chartered Accountant appeared on behalf of the assessee on various dated and the case was discussed. The Power of Attorney filed by the assessee representative was placed on file. The assessee is trust established by the trust deed dated 11/8/2005 with the primary objective of propagating meditation and spiritual research centers etc. The trust is Registered u/s 12A of the Income-tax Act by the order of the Director of Income-tax (Exemption) vide order in No. DIT (E)/ 12A/ Vol-III /N-289 /W-2 /05-06, dated 20/1/2006. The copy of trust deed and the 12A Registration submitted by the assessee is verified and placed on file.
During the course of scrutiny details were called on the bank accounts, list of donors with the name and addresses etc. The copies of sale deed/gift deed are called for the verification of donations received in kind. The photo copies of the mediation campus expenses and work in progress etc submitted by the assessee for verification. The various bank accounts held by the assessee with the passbook extracts called for also submitted. Further details on building materials produced by the assessee. All the above referred details submitted by the assessee is verified and placed on file
MB _ [signature] _ Cont... 3
Trust Name: DHYANAPEETA CHARITABLE TRUST
The closed assessment case of DHYANAPEETA CHARITABLE TRUST was reopened for Assessment Years 2005-06, 2006-07, 2007-08, 2008-09 and 2009-10.
For all these years the Assessing Officer (AO) was of the belief that income had escaped assessment by wrongful claims and claiming double deduction. Also, that the receipts and payments account does not give a true and accurate picture of the money received and deposited. The assessing officer completed the report by making a huge addition to the numbers, thereby raising a demand of around 32 lakhs on the trust.
The Commissioner of Income tax has himself stated that the action of the AO is not sustainable in the eyes of the law. The whole intention behind the actions of the Income tax department gave an indication that it was merely to harass and put pressure on His Divine Holiness and His community, threatening their very sustainability and quality of life.
The first line on the fourth page of the assessment of this case states, in the direct words of the Commissioner:
"It is submitted that the Learned Assessing Officer has no tangible evidence which is newly coming to his possession for the purpose of forming a belief that income tax has escaped his assessment."
Here is one excerpt from the 18-page report, dismissing the case:
| Trustees, Dhyanapeetha Charitable Trust | Date: 26.2.2014 | | ITA No.1100 & 1101/ Trust/CIT(A)-V/2011-12 | A.Y : 2005-06 & 2006-07 |
cases also, it has been held that even in the earlier case of proceeding, under section 143 (1) of the IT Act, re-assessment cannot be initiated without the existence of tangible evidence.
- As may be seen from the reasons, it is clear that the reasons are devoid of any tangible evidence. The reasons are simply based on the information which is conspicuously mentioned in the financial statements. It is not the case of information which is hidden under the reams of paper. Instead, it is an obvious information which is clearly and conspicuously seen on the face of the financial statements. It is further submitted that the so-called tangible evidence will have to come from the external source as held by the Honourable Karnataka High Court in the case of CIT vs. Ramakrishna Hegde [2010] 326 ITR 347 (Karn) HC.
- It is submitted that the Learned Assessing Officer has erred in completing the re-assessment without disposing the objections against re-opening of assessment submitted by the Appellant for re-opening the assessment. The Honourable Supreme Court in the case of GKN Driveshafts (India) Ltd. vs. CIT (2003) 259 ITR 19 (SC) has held that the assessing officer is bound to dispose of the objection filed by the assessee by passing a speaking order.
- The object of the AO's order/separate order disposing of the objections is to enable the assessee to file a writ petition in the respective High Court, if so advised, before the assessment order is passed, challenging the legality of the said notice u/s. 148 and the assessment sought to be framed in consequence thereof. The Hon'ble Delhi High Court in Smt. Kamlesh Sharma v. B.L. Meena ITO [(2006) 287 ITR 337 (Del)] their Lordships took a very strong view of the AO not following the procedure prescribed by the Hon'ble Supreme Court in the case of GKN Driveshafts case (supra) and imposed a cost of Rs. 3,500/- on the Department. They laid down the following proposition of law: "We are of the opinion that in view of the language of the Supreme court in GKN Driveshafts (India) Ltd. vs. CIT (2003) 259 ITR 19, the Assessing Officer should have rejected the objection, if he thought it appropriate to do so, before passing the final order and not simultaneously." We also draw the attention of the Learned Commissioner (A) to the case of Hameed, Mangalore v. Department of Income-tax, ITAT, Bangalore Order dated 28.9.2011 in ITA No.511 to 516/Bang/2009 on the subject matter.
12. Therefore, it is our submission that the re-assessment order passed by the Learned Assessing Officer is bad in law and therefore the same is liable to be quashed.
III. As regards disallowing expenditure claimed as per Receipts and Payments Account and considering amount as per Income and Expenditure Account:
1. Learned A.O. erred in forming opinion that the assessee's account create a lot of confusion and rejecting the Receipts and Payments account. He failed to appreciate the interplay between the R & P Account and the I & E Account.
2. We submit that the assessee has consistently claimed both revenue and capital expenditure on actual payment basis. The application of donation received in kind during the same year is added by the assessee to this amount as per the R & P Account. Therefore, if the claim is allowed as per I & E Account instead of R & P Account there will be an inconsistency. Further, the expenditure which was incurred in an old previous year, not allowed in any previous years due to balance lying as Sundry Creditors will never get allowed when actually paid in this year. This amount will not be allowed in any other previous years as well.
3. The learned A.O. in his assessment order has made an observation that fixed assets additions in the R & P account and the fixed assets schedule does not match. But he failed to appreciate the
TRUST NAME: NITHYANANDESHWAR DEVASTHANAM TRUST
Till the Financial Year 2009, no case against Nithyanandeshwar Devasthanam Trust was ever selected for assessment. Suddenly, during the persecution time, however, in the month of August, 2010, the Income Tax Department issued notice u/s.148 of the Income tax Act for Assessment years 2006-07, 2007-08 and 2008-09, stating that the Trust has violated the conditions of Sec.11(2) of the Income tax Act and has escaped income. In this process, they raised a huge demand.
However, the ld. CIT(A)V, (Commissioner of Income Tax (Appeals)) Bangalore had passed a very crisp order deleting the entire demand raised by the Assessing Officer. The conclusion of the appellate order is reproduced below, very clearly showing that the cases were re-opened without any basis, just for the sake of harassment. This is just one small excerpt from a 6-page document proclaiming the innocence of the Trust:
TRUST NAME: NITHYA GNANADHAN TRUST
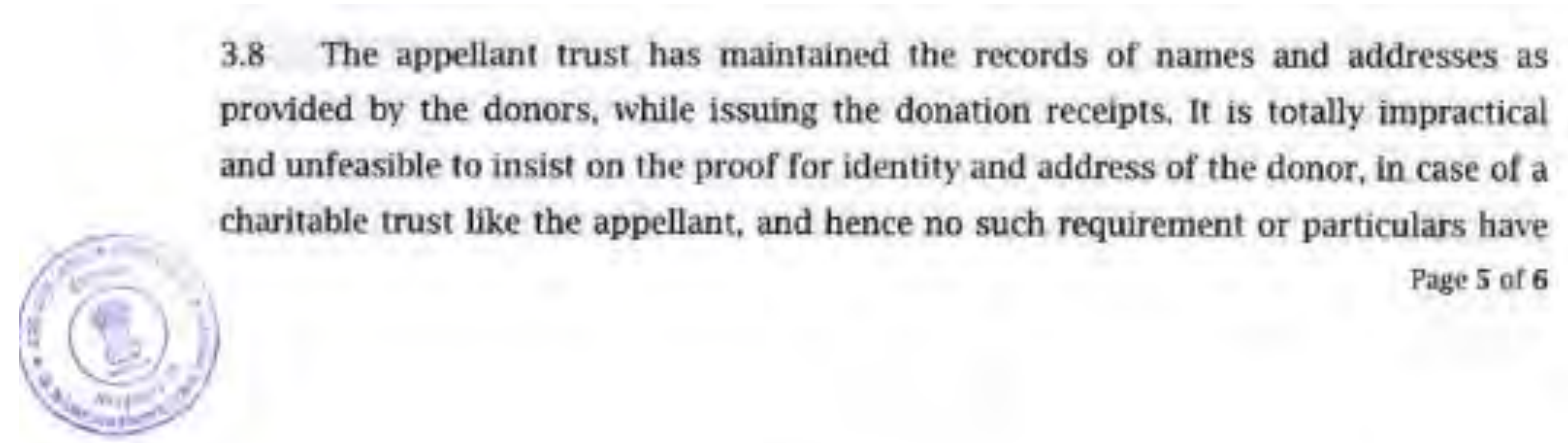
Nithya Gnanadhan Trust, the charitable trust opened to provide free books, literature, translations of sacred texts and more, was also re-opened for two years 2007-08 AND 2008-09 for the reason that some anonymous donations have been received and also that foreign donations have been received without registration under FCRA.
Till 2010, none of the cases were re-opened. Suddenly, in August 2010, these two years of cases were re-opened. Demand was raised by the Assessing Officer claiming that the accumulation of income claimed by the assessee u/s 11(2) of the IT (Income tax) Act is not adhered to in the formalities and that there appears to be certain anonymous donations. Hence notice u/s 148 was issued on the assessee on 18/8/2010, to assess the income 'escaped'.
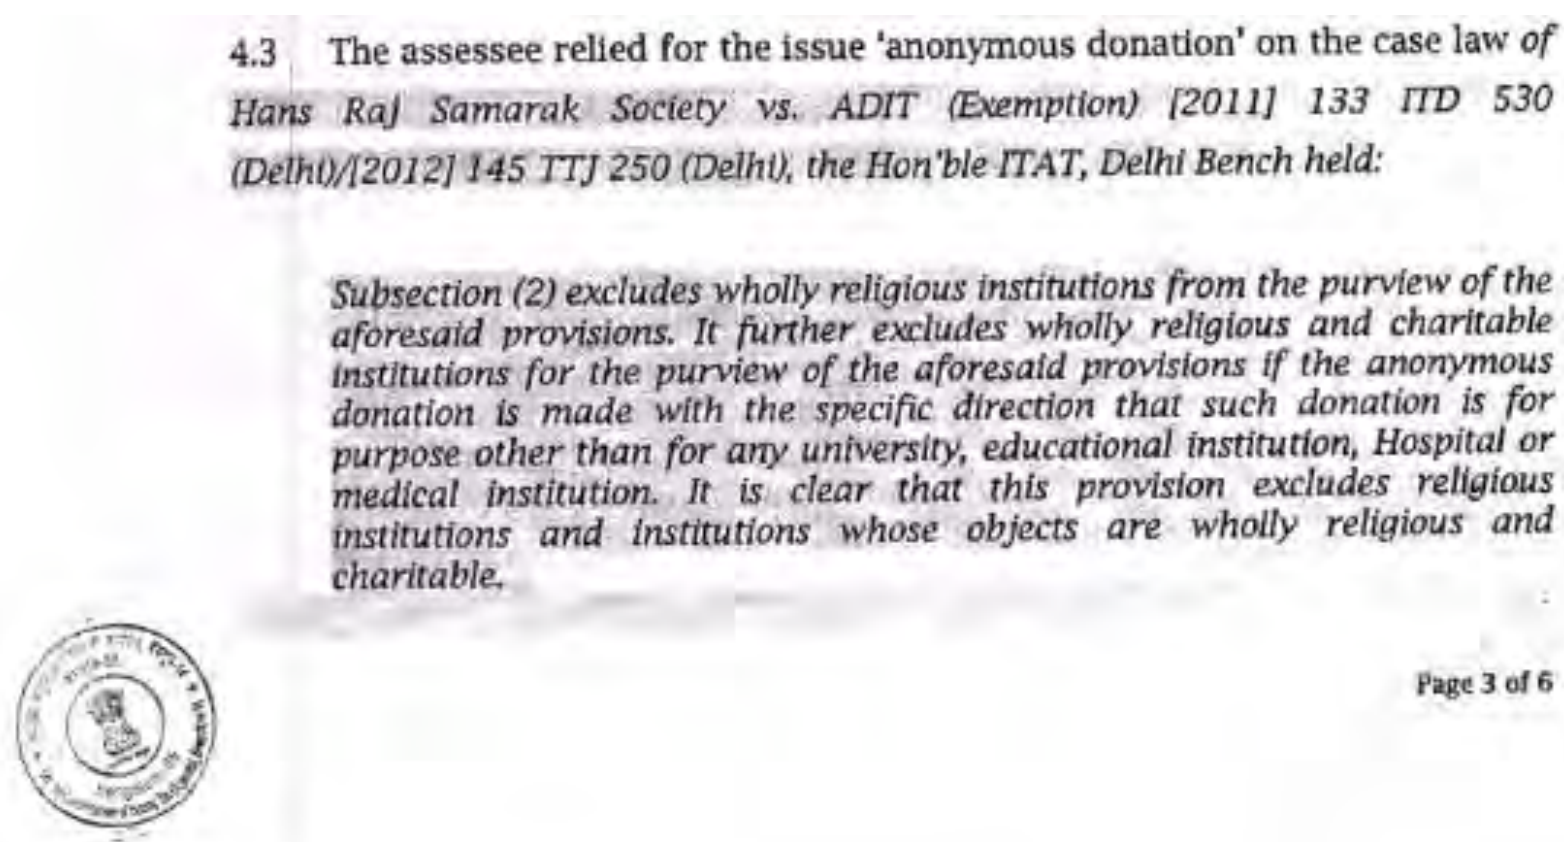
The Assessing Officer raised a huge demand. The ld. CIT(A) did due diligence to the trust by applying the Income tax Rules meticulously to the case, and granted the trust a huge victory in this false case. An excerpt of his conclusions are reproduced below:
> 4.3 The assessee relied for the issue 'anonymous donation' on the case law of Hans Raj Samarak Society vs. ADIT (Exemption) [2011] 133 ITD 530 (Delhi)/[2012] 145 TTJ 250 (Delhi), the Hon'ble ITAT, Delhi Bench held: Subsection (2) excludes wholly religious institutions from the purview of the aforesaid provisions. It further excludes wholly religious and charitable institutions for the purview of the aforesaid provisions if the anonymous donation is made with the specific direction that such donation is for purpose other than for any university, educational institution, Hospital or medical institution. It is clear that this provision excludes religious institutions and institutions whose objects are wholly religious and charitable.
Page 3 of 6
Police silently slips a memo declaring that no evidence was found against His Divine Holiness - The case is about to be quashed.
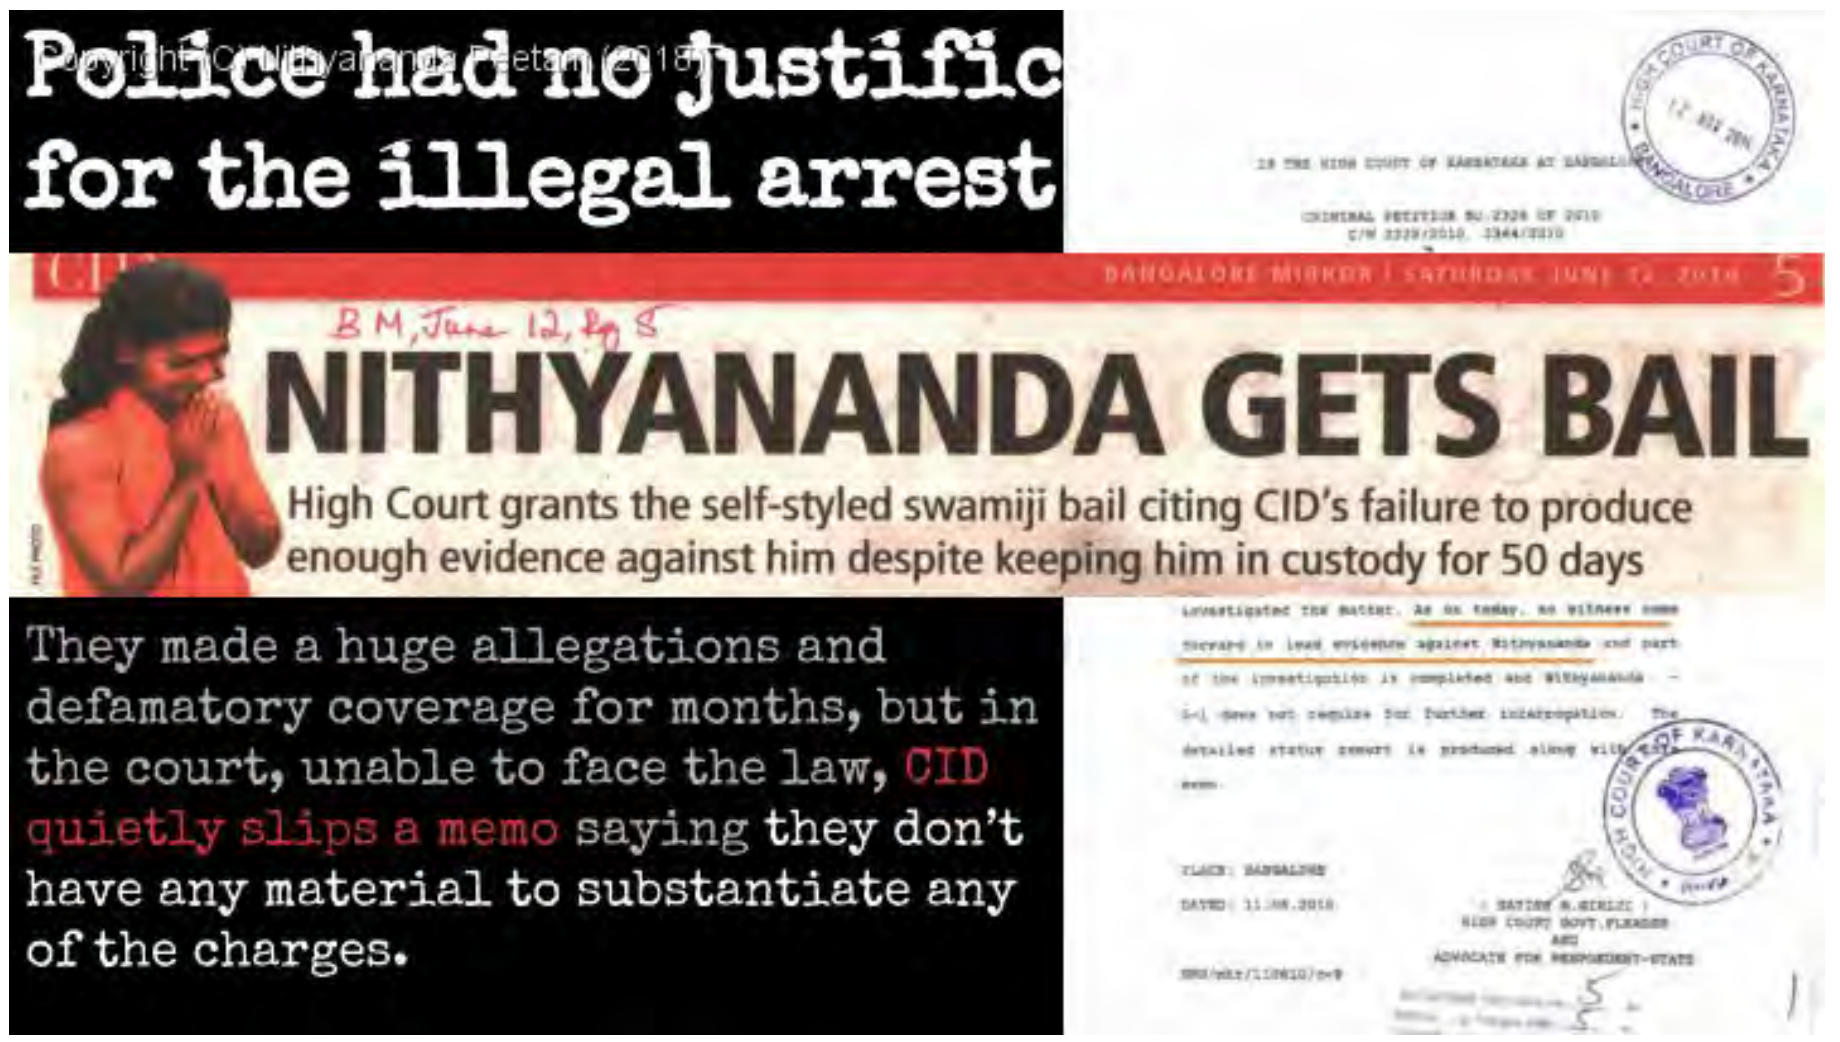
As per the High Court Proceedings written excerpt from 23 July 2010 hearing of the quash petition filed in Crl.P. 1231/2010 "...there is no material for the offences under Sections 376 and 420 IPC".
nan demanded a hike to Rs8 per-
after the first two, and a mini-
N6. What the DC has announced
we are more than satisfied," he
on be the target of vicious at-
the KRV and Jaya Karnataka set
as for his remarks. The meeting
roffice became a war zone. Mem-
their seats and rushed towards
DC summoned the police and left
all.
the protesters to move outside
ne DC, Abbas too was heading out,
tagitator caught hold of him and
in front of police personnel.
d injury in the left ear. His shirt
[email protected]
nounced by Bangalore Urban
deputy commissioner MK
Ayyappa, the Karnataka Rak-
shana Vedike (KRV) and Jaya
Karnataka activists have
called a complete bandh of
autorickshaws in the city
from Monday. "We will meet
Karnataka activists have
Saturday and discuss the
need for reconsidering this
decision. If the deputy
commissioner does not agree,
then we will be left with
no option but to call a com-
plete bandh of autos," said
activists.
Jaya Karnataka leader
Jaitram said that even a hike
of the minimum fare to Rs18,
and the per kilometre fare af-
ter the first two kilometres to
Rs9 may have been accept-
Anantha Subrahmanyam R
able. "However, the current
revision is unacceptably low,"
he said.
Somashekar, president of
the Bangalore Auto Drivers
reconsider his decision. If he
does not agree, the union
leaders and members will sit
together and chalk out a
course of action. We will also
meet transport minister R
Ashok and convince him of
the justness of our demands,"
he said.
Transport minister R
Ashok, who is away in
Mandya district, said that the
government could not be held
responsible for ruckus at the
DC's office on Friday. "It's a
fight between auto unions,
not something that the gov-
ernment is involved with," he
said.
away to safety
Activists from KRV and Jaya
Karnataka shouted at Md Ab-
bas, the dissenting voice
among auto drivers'
unions.Police managed to
convince the protesters to
move out of the hall. Abbas
too emerged. An angry pro-
tester caught hold of him and
thrashed him, right in front of
the police. Abbas suffered in-
jury in the left ear; his clothes
were torn. Police resorted to
lathicharge.
Abbas was whisked away
to safety from the rear of the
DC's office.
[email protected]